-
-
Tax Services
-
Audit & Assurance
-
Business Setup
-
Accounting & Payroll
-
Advisory
-
The Institute of Company Secretaries of India (ICSI) has requested the Ministry of Corporate Affairs (MCA) to extend the filing due dates for various other statutory e-forms under the Companies Act, 2013, and the Limited Liability Partnership Act, 2008, up to 31 December 2026 without additional fees.
In its representation dated 28 October 2026, bearing reference number G&CL: MCA: OCT:02/2026, ICSI highlighted several technical difficulties faced by companies and professionals while using the MCA-21 V3 portal. These include frequent portal downtime, login failures, session timeouts, Digital Signature Certificate (DSC) association problems, form validation errors and payment processing failures.
The requested extension covers forms such as ADT-1, MGT-14, DIR-12, MR-1, MR-2, CRA-2, MSME Form I, PAS-6, LLP Form 8 and certain forms relating to One Person Companies (OPCs).
However, the proposed MCA filing due date extension is currently a request made by ICSI, not an approved extension granted by MCA. Companies and LLPs should continue to follow their applicable statutory deadlines unless the Ministry issues a formal circular providing further relaxation.
ICSI has submitted a fresh representation to the Ministry of Corporate Affairs on 28 October 2026, requesting an extension of due dates for various statutory e-forms that were not covered under the earlier MCA filing relaxations.
The Institute has requested that statutory forms falling due between 1 October and 31 October 2026 be permitted for filing up to 31 December 2026 without payment of additional fees.
The representation was addressed to Dr. Pallavi Jain Govil, Secretary, Ministry of Corporate Affairs, and signed by ICSI President CS Pawan G. Chandak.
The request follows the Ministry’s earlier decisions to extend the filing period for specified annual filing forms and Form CRA-4. However, several other statutory filings remain outside those specific relaxations.
| Particulars | Details |
|---|---|
| Representing organisation | Institute of Company Secretaries of India (ICSI) |
| President | CS Pawan G. Chandak |
| Addressed to | Dr. Pallavi Jain Govil, Secretary, MCA |
| Letter reference | G&CL: MCA: OCT:02/2026 |
| Date of representation | 28 October 2026 |
| Proposed extended deadline | 31 December 2026 |
| Requested fee relaxation | Filing without additional fees |
| Original due-date window | 1 October to 31 October 2026 |
| Primary reason | Technical difficulties on the MCA-21 V3 portal |
The purpose of this representation is to provide companies, LLPs and compliance professionals with additional time to complete statutory filings without facing additional financial liabilities arising from portal-related difficulties.
It is important to distinguish this representation from ICSI’s earlier letter dated 9 October 2026, which focused on extending the deadlines for annual filing forms such as AOC-4 and MGT-7.
The 28 October representation specifically addresses other statutory e-forms that were not covered by the earlier MCA circulars.
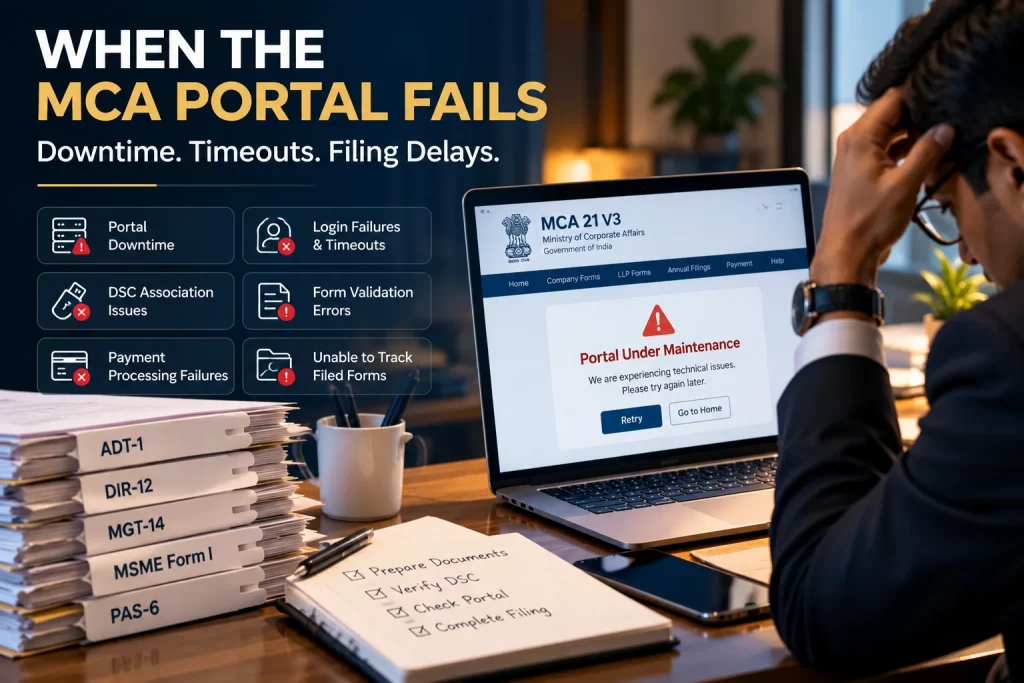
The primary reason behind ICSI’s request is the technical and operational difficulties reportedly experienced by stakeholders while filing forms through the MCA-21 V3 portal.
The online filing system is an essential part of corporate compliance in India. Companies must use it to submit statutory information relating to directors, auditors, resolutions, share capital, managerial appointments and other regulatory requirements.
When the portal experiences technical problems, the impact goes beyond inconvenience. A company may be unable to complete a filing even after preparing the necessary documents and obtaining the required approvals.
ICSI has highlighted the following issues in its representation.
Companies and professionals have reported frequent portal downtime and slow response times while accessing the MCA-21 V3 system.
This becomes particularly problematic when multiple statutory filings are due within a limited period. Even if the company has completed its internal compliance procedures, portal unavailability can prevent the final submission of the relevant e-form.
Consequently, businesses may face delays in completing their statutory obligations despite having prepared the required information in advance.
Login and user-management difficulties can interrupt the filing process before a form is successfully submitted.
Session timeouts create an additional challenge when users are entering company information, uploading supporting documents or completing lengthy forms.
Repeated interruptions can require professionals to restart the filing process, verify information again and spend additional time completing the same compliance activity.
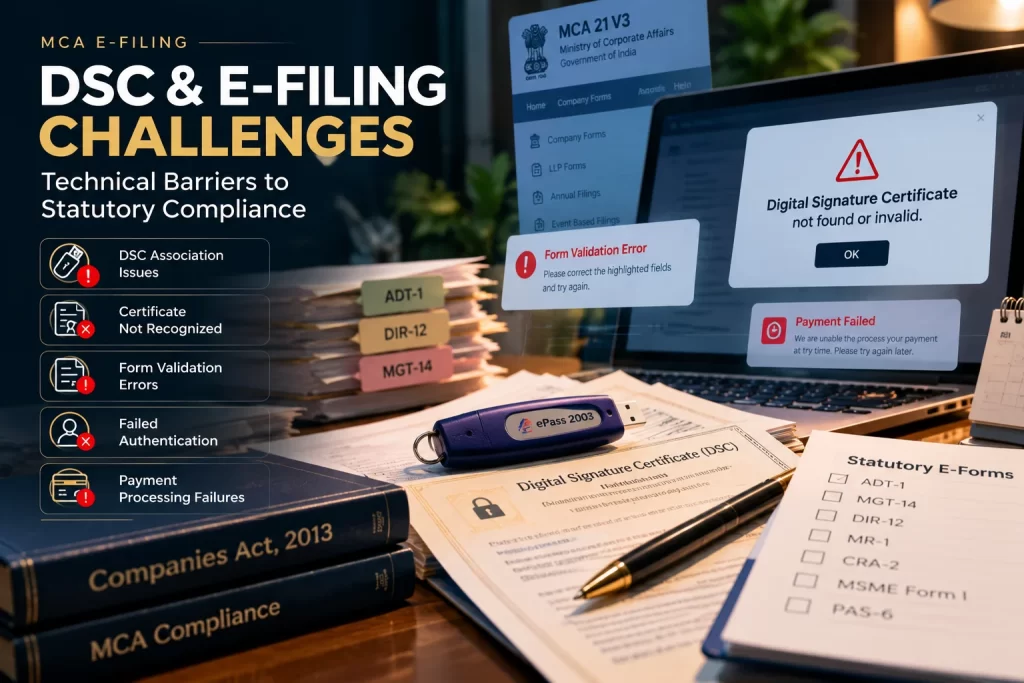
A Digital Signature Certificate is an important requirement for authenticating and submitting several MCA statutory forms.
ICSI has highlighted difficulties in associating DSCs with the relevant user accounts.
Such problems can prevent authorised directors and professionals from completing the authentication process even when the form has been correctly prepared.
For companies with several directors or authorised signatories, DSC-related difficulties can create further delays in completing time-sensitive filings.
Form validation errors can prevent users from proceeding with statutory submissions.
These errors may arise during the verification of entered information, supporting documents or other form requirements.
When the portal fails to validate a form, users may need to review the information, identify the issue and attempt submission again. This can increase the time required to complete filings and create uncertainty when statutory deadlines are approaching.
Payment-related failures can interrupt the final stages of the e-filing process.
A company may experience difficulties while completing payment or confirming whether a transaction has been successfully processed.
This can create uncertainty regarding the status of the filing and may require additional verification to avoid duplicate payments or incomplete submissions.
ICSI has also highlighted difficulties in accessing and tracking forms that have already been filed.
The ability to verify filing status, retrieve acknowledgements and track Service Request Numbers (SRNs) is essential for maintaining proper corporate compliance records.
If users cannot access this information, it becomes more difficult to confirm whether a statutory filing has been successfully completed.
Overall compliance impact: These portal-related difficulties can delay statutory submissions, increase administrative work, create uncertainty regarding filing status and expose companies to additional filing fees. This is why ICSI has requested an extension to allow stakeholders to complete their filings without being adversely affected by the reported technical problems.
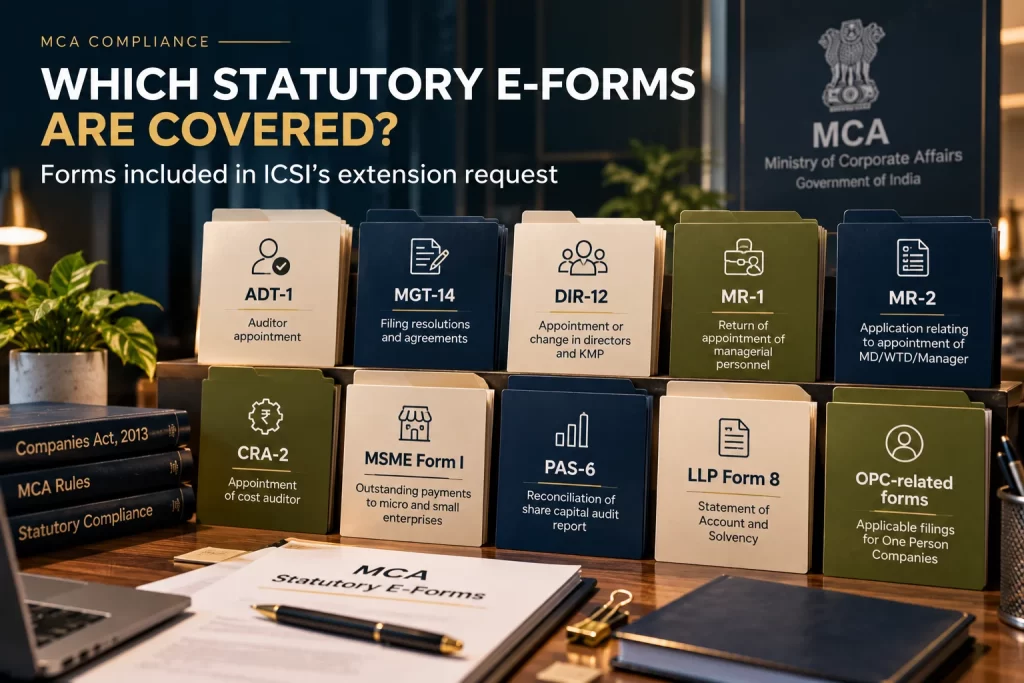
ICSI has specifically identified several statutory e-forms in its representation dated 28 October 2026.
These forms relate to different corporate compliance requirements, including auditor appointments, board resolutions, director changes, managerial appointments, cost audits, outstanding MSME payments and LLP financial disclosures.
The following table explains the forms mentioned in the representation and their general purposes.
| Form | Purpose |
|---|---|
| ADT-1 | Intimation of appointment of an auditor |
| MGT-14 | Filing specified resolutions and agreements with the Registrar of Companies |
| DIR-12 | Filing particulars relating to the appointment, resignation or changes in directors and Key Managerial Personnel (KMP) |
| MR-1 | Return of appointment of managing director, whole-time director or manager |
| MR-2 | Application relating to approval of appointment or reappointment of managing director, whole-time director or manager, where applicable |
| CRA-2 | Intimation of appointment of cost auditor |
| MSME Form I | Half-yearly return concerning outstanding payments to micro and small enterprises |
| PAS-6 | Reconciliation of share capital audit report |
| LLP Form 8 | Statement of Account and Solvency |
| OPC-related forms | Applicable statutory filings relating to One Person Companies |
These are examples specifically identified in the ICSI representation, not an exhaustive list of all statutory forms.
The applicability and original statutory due date of each form should be verified according to the relevant provisions and the circumstances of the company or LLP.
ADT-1: Generally required within 15 days of the relevant auditor appointment resolution. Companies should verify the applicable appointment requirements under Section 139 of the Companies Act, 2013.
MGT-14: Specified resolutions and agreements must generally be filed within 30 days under Section 117, subject to applicable exemptions.
DIR-12: Generally required within 30 days of the relevant appointment, resignation or change relating to directors and KMP under Section 170 and the applicable rules.
MR-1: Generally filed within 60 days of the appointment of managerial personnel, subject to the applicable requirements.
MR-2: Relates to applications for Central Government approval in applicable cases concerning managerial appointments and their terms.
CRA-2: Relates to the appointment of a cost auditor. The applicable filing timeline depends on the circumstances and relevant cost audit requirements.
MSME Form I: This half-yearly return covers specified outstanding payments to micro and small enterprises. The normal due dates are 31 October for the April–September period and 30 April for the October–March period.
PAS-6: Relates to half-yearly reconciliation of share capital. It is generally required within 60 days from the end of the relevant half-year. Its usual second-half filing deadline falls in November, so it should not automatically be treated as an October-due form.
LLP Form 8: Relates to the Statement of Account and Solvency of an LLP and is generally due within 30 days from the end of six months of the financial year.
OPC-related forms: ICSI has referred to forms relating to One Person Companies but has not individually identified every form number in the representation. Therefore, additional form numbers should not be assumed.
ICSI has requested that eligible statutory e-forms falling due between 1 October 2026 and 31 October 2026 be permitted for filing up to 31 December 2026 without additional fees.
The proposed relaxation is intended to provide additional time to companies and LLPs that have faced difficulties completing statutory submissions through the MCA-21 V3 portal.
The requested extension can be understood through the following details:
| Particulars | Proposed position |
|---|---|
| Original due-date window | 1 October 2026 to 31 October 2026 |
| Requested extended deadline | 31 December 2026 |
| Additional filing fee | Requested waiver |
| Forms covered | Other statutory e-forms identified in the representation |
| Current status | Request submitted to MCA; separate approval required |
It is important to understand that the requested date of 31 December 2026 is not yet an automatically applicable revised deadline for these forms.
The actual statutory deadline for each form continues to apply unless MCA issues a formal relaxation covering that particular filing.
No corresponding MCA circular granting the extension requested in ICSI’s representation dated 28 October 2026 had been identified as of 30 October 2026.
The distinction between a request submitted by a professional body and an extension officially granted by the Ministry is important for companies and LLPs.
ICSI has requested the Ministry to provide additional time for statutory e-form submissions. However, submitting a representation does not automatically change the filing deadlines prescribed under the Companies Act, 2013 or the LLP Act, 2008.
A formal MCA circular or other applicable government notification is necessary to establish the requested relaxation.
An ICSI representation is a formal request submitted by the professional institute to the Ministry, highlighting difficulties faced by its members and other stakeholders.
An MCA General Circular, on the other hand, is an official communication issued by the Ministry that can provide specified regulatory clarifications or filing relaxations.
Therefore, companies should not consider the proposed deadline of 31 December 2026 as approved merely because ICSI has requested it.
| Filing category | Current position as of 30 October 2026 |
|---|---|
| Specified AOC-4 forms | Extension granted under General Circular No. 05/2026 |
| MGT-7 and MGT-7A | Extension granted under General Circular No. 05/2026 |
| CRA-4 | Extension granted under General Circular No. 06/2026 |
| ADT-1 | Included in ICSI's request; no corresponding approval identified |
| MGT-14 | Included in ICSI's request; no corresponding approval identified |
| DIR-12 | Included in ICSI's request; no corresponding approval identified |
| Other forms mentioned by ICSI | Requested relief; no corresponding approval identified |
Companies should regularly monitor the official MCA website for any subsequent announcement.
Until the Ministry issues a relevant circular, businesses should continue to comply with the applicable statutory filing requirements.
The recent developments concerning MCA filing extensions should be understood as two separate sets of developments.
First, MCA has already granted relief for specified annual filing forms and CRA-4 through General Circular Nos. 05/2026 and 06/2026.
Second, ICSI has submitted another representation on 28 October 2026 requesting similar relief for other statutory e-forms.
The following comparison explains the difference.
| Particulars | Existing MCA filing relief | New ICSI request |
|---|---|---|
| Authority | Ministry of Corporate Affairs | Institute of Company Secretaries of India |
| Relevant reference | General Circular No. 05/2026 and 06/2026 | G&CL: MCA: OCT:02/2026 |
| Date | 24 and 27 October 2026 | 28 October 2026 |
| Forms covered | Specified AOC-4 variants, MGT-7, MGT-7A and CRA-4 | ADT-1, MGT-14, DIR-12, MR-1, MR-2, CRA-2, MSME Form I, PAS-6, LLP Form 8 and OPC-related forms |
| Deadline | 31 December 2026 for specified AOC-4 forms and CRA-4; 31 January 2027 for MGT-7 and MGT-7A | Requested extension up to 31 December 2026 |
| Additional fees | Relaxation granted for the specified forms within the prescribed period | Waiver requested, but not automatically approved |
| Legal status | Officially granted | Representation awaiting MCA decision |
On 24 October 2026, MCA issued General Circular No. 05/2026, granting relaxation for specified financial statement and annual return filings for FY 2025-26.
The revised dates are:
| Form | Revised deadline without additional fees |
|---|---|
| AOC-4 | 31 December 2026 |
| AOC-4 (CFS) | 31 December 2026 |
| AOC-4 (XBRL) | 31 December 2026 |
| AOC-4 NBFC (Ind AS) | 31 December 2026 |
| AOC-4 CFS NBFC (Ind AS) | 31 December 2026 |
| MGT-7 | 31 January 2027 |
| MGT-7A | 31 January 2027 |
The circular does not extend the statutory deadline for conducting an Annual General Meeting.
It also specifies that filings made after the extended period will attract applicable fees, including additional fees, calculated from the original statutory due date.
On 27 October 2026, MCA issued General Circular No. 06/2026, providing relief for filing Form CRA-4 for FY 2025-26.
Eligible companies can submit CRA-4 up to 31 December 2026 without additional fees under this circular.
Although ICSI’s earlier representation dated 9 October 2026 requested relief for certain annual filing forms and ADT-1, the subsequent General Circular No. 05/2026 did not include ADT-1 or DIR-12.
This is an important distinction.
The relief granted for AOC-4, MGT-7, MGT-7A and CRA-4 should not be interpreted as a general extension covering all statutory e-forms.
The 28 October representation is intended to address this remaining gap by requesting additional time for other filings affected by MCA-21 V3 portal difficulties.
Although ICSI has requested an extension, companies and LLPs should not postpone their compliance activities based on an anticipated relaxation.
Businesses should continue preparing and submitting statutory forms within their existing applicable deadlines unless MCA formally announces a different filing period.
The following precautions can help reduce the risk of additional fees and filing complications.
Prepare a list of all pending statutory forms and identify the applicable filing deadlines.
The due dates may differ depending on the form, relevant board resolution, appointment, financial year or other statutory event.
Companies should not assume that all forms mentioned in ICSI’s representation have the same original due date.
Prepare the necessary supporting documents before initiating the online filing process.
Depending on the form, these may include board resolutions, shareholder resolutions, appointment letters, auditor consent documents, financial statements, share capital information and other relevant records.
Keeping these documents ready can help reduce delays when the portal is operational.
Check whether the relevant Digital Signature Certificates are valid and properly associated with the authorised user accounts.
Companies should also verify that the appropriate director or authorised signatory is available to complete the authentication process.
This can help prevent last-minute DSC-related issues.
If a statutory filing cannot be completed because of technical difficulties, companies should maintain proper evidence of the issue.
Relevant records may include:
These records can help demonstrate the steps taken by the company to complete its statutory compliance.
However, maintaining evidence of a portal error does not automatically waive additional fees or statutory consequences.
ICSI has requested filing relief without additional fees, but the request itself does not grant a waiver.
Companies should calculate applicable filing fees according to the existing statutory provisions and relevant MCA fee rules.
Any subsequent relaxation should be interpreted according to the specific forms, dates and conditions mentioned in the official circular.
Where the portal is operational, companies should attempt to complete their statutory filings within the prescribed period.
Waiting for an extension announcement without taking necessary compliance steps can expose businesses to avoidable additional fees.
Regularly check the MCA website for new general circulars, notifications and clarifications.
The official announcement should be reviewed before changing any internal compliance calendar or treating a requested deadline as an approved extension.
Managing corporate statutory compliance requires proper coordination between company records, financial information, board approvals, authorised signatories and online filing procedures.
Technical difficulties on the MCA-21 V3 portal can make this process more challenging, particularly when multiple statutory forms are due within a limited period.
GVC Audit can assist businesses in reviewing their corporate compliance requirements and identifying filing-related issues that may require professional attention.
A review of pending statutory obligations can help businesses identify the forms applicable to their company, their original filing deadlines and the supporting documentation required.
Proper preparation of board resolutions, appointment records, financial information and other supporting documents can help reduce errors during the filing process.
Reviewing form details, authorisations, supporting documents and applicable filing requirements before submission can help identify potential discrepancies.
Businesses can review their existing filing position and understand the potential additional fee implications of delayed statutory submissions under the applicable rules.
Companies dealing with multiple pending filings or complex compliance requirements may benefit from professional assistance in coordinating the necessary statutory procedures.
Is your company facing MCA filing difficulties or struggling to manage pending statutory e-forms?
Contact GVC Audit for professional assistance with corporate compliance, documentation and statutory filing requirements.
As of 30 October 2026, no corresponding MCA circular granting the requested extension has been identified. ICSI has requested an extension up to 31 December 2026, but companies should continue following the applicable statutory deadlines until MCA formally announces any relaxation.
The representation identifies ADT-1, MGT-14, DIR-12, MR-1, MR-2, CRA-2, MSME Form I, PAS-6, LLP Form 8 and forms relating to One Person Companies.
ICSI has requested that eligible statutory e-forms falling due between 1 October and 31 October 2026 be permitted for filing up to 31 December 2026 without additional fees.
ICSI has highlighted technical problems on the MCA-21 V3 portal, including downtime, slow response, login failures, session timeouts, DSC association difficulties, form validation errors, payment failures and problems accessing filed forms.
No. General Circular No. 05/2026 covers specified AOC-4 variants and MGT-7/MGT-7A. ADT-1 was not included in that circular, which is one of the reasons ICSI has sought further relief.
ICSI’s representation dated 28 October 2026 highlights the difficulties faced by companies, LLPs and compliance professionals while completing statutory filings through the MCA-21 V3 portal.
Although MCA has already provided filing relief for specified AOC-4 forms, MGT-7, MGT-7A and CRA-4 through General Circular Nos. 05/2026 and 06/2026, several other statutory e-forms remain outside those specific relaxations.
ICSI has therefore requested the Ministry to extend the filing period for other statutory e-forms up to 31 December 2026 without additional fees.
However, the requested MCA filing due date extension is not an approved relaxation as of 30 October 2026. Companies should continue to monitor their statutory deadlines, prepare the required documentation and complete filings under the currently applicable rules.
Timely compliance, proper documentation and professional review can help businesses reduce filing errors and avoid unnecessary additional fee liabilities.