-
-
Tax Services
-
Audit & Assurance
-
Business Setup
-
Accounting & Payroll
-
Advisory
-
If you are searching for the GSTR-9 due date extended for FY 2025–26, the key point is this: the normal statutory deadline for filing GSTR-9 and the applicable GSTR-9C is 31 December 2026. As of 7 November 2026, we have not verified an official notification extending this deadline.
The annual return filing window is already open. GSTN enabled GSTR-9 and GSTR-9C for FY 2025–26 on 8 October 2026. Businesses should therefore start reconciling their records rather than wait for a possible extension.
The annual return is not simply a summary of the figures already reported during the year. It is an opportunity to review turnover, tax liability, input tax credit (ITC) and differences between GST returns and the books of accounts before completing the filing process.
This guide from AVC India explains the GSTR-9 due date for 2026, the applicability of GSTR-9 and GSTR-9C, the reconciliation process, the records businesses should prepare and the important checks to complete before filing.
As of 7 November 2026, an official extension has not been verified. Businesses should work towards the normal due date of 31 December 2026 unless the Government issues an applicable extension.
The due date is prescribed under Rule 80 of the Central Goods and Services Tax (CGST) Rules, 2017. Under the normal rule, GSTR-9 must be furnished by 31 December following the end of the relevant financial year. Where GSTR-9C is applicable, it must be furnished along with the annual return within the prescribed deadline.
Some professional associations have requested an extension to 31 March 2027. However, a request for an extension does not change the legal deadline. Taxpayers should rely on an applicable government notification rather than an announcement about a proposal or a prediction that the date may be extended.
For the latest position, check the official GST portal and the CBIC website.
What should businesses do now?
The safest approach is to prepare for the existing deadline and adjust the compliance calendar only if an official extension is notified.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
| Particulars | Normal Deadline |
|---|---|
| Financial Year Covered | 1 April 2025 to 31 March 2026 |
| GSTR-9 Annual Return | 31 December 2026 |
| GSTR-9C Reconciliation Statement (Where Applicable) | 31 December 2026 |
| GSTN Portal Availability | From 8 October 2026 |
| Extension Status | No Official Extension Verified as of 7 November 2026 |
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
GSTR-9 is the annual GST return that brings together information about a registered taxpayer’s activities during a financial year.
It includes information relating to outward supplies, inward supplies, input tax credit, tax paid and other relevant particulars reported through the GST return system. It helps businesses review their annual GST position against the returns filed during the year.
For example, a business may report sales of ₹80 lakh in its accounting records but find that the annual figures in its GST returns differ because of credit notes, amendments, timing differences or classification issues.
These differences should be investigated and documented before filing the annual return. A difference does not automatically mean that tax has been underpaid, but an unexplained difference should not be ignored.
GSTR-9 should therefore be prepared using the books of accounts, filed returns and supporting documents, rather than by accepting every auto-populated figure without review
GSTR-9C is the reconciliation statement used to reconcile the figures reported in the annual GST return with the relevant financial statements.
It is applicable to eligible registered taxpayers whose aggregate turnover during the financial year exceeds ₹5 crore, subject to the exclusions under the applicable provisions.
GSTR-9C is self-certified under the current framework. It is not the same as the earlier mandatory GST audit certification regime.
The reconciliation statement is particularly important for businesses with multiple branches, substantial transaction volumes, significant ITC claims or differences between accounting revenue and GST turnover.
Before preparing GSTR-9C, the business should ensure that the financial statements are finalised and that the figures in the annual return can be supported by proper reconciliation workings.
The filing requirement depends on the taxpayer’s registration category, aggregate turnover and applicable exemptions.
For FY 2025–26, the general position is that registered taxpayers with aggregate turnover exceeding ₹2 crore must file GSTR-9, subject to the applicable exclusions and exemptions.
Notification No. 15/2025–Central Tax introduced an exemption from filing the annual return for taxpayers with aggregate turnover up to ₹2 crore for the relevant financial years from FY 2024–25 onwards. Taxpayers should verify the notification and their eligibility before concluding that filing is not required.
Registered taxpayers whose aggregate turnover exceeds ₹5 crore during the financial year are generally required to furnish GSTR-9C along with GSTR-9, subject to the exclusions specified in the law.
| Aggregate Turnover in FY 2025–26 | General Filing Position |
|---|---|
| Up to ₹2 crore | Annual-return exemption generally applies, subject to the applicable notification and eligibility. |
| Above ₹2 crore and up to ₹5 crore | GSTR-9 generally applies; GSTR-9C is generally not required. |
| Above ₹5 crore | GSTR-9 and GSTR-9C generally apply. |
Aggregate turnover is determined under GST law on a PAN-wide basis, not simply by looking at the sales of one branch or GST registration in isolation.
Certain categories, including Input Service Distributors, specified taxpayers under Sections 51 and 52, casual taxable persons and non-resident taxable persons, are subject to different provisions or exclusions. Businesses should confirm their category before applying the general table.
For the legal provisions, refer to Rule 80 of the CGST Rules.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
| Basis | GSTR-9 | GSTR-9C |
|---|---|---|
| Purpose | Annual GST return | Reconciliation of annual-return figures with financial statements |
| General Turnover Threshold | Above ₹2 crore, subject to exemptions | Above ₹5 crore, subject to exclusions |
| Main Information | Supplies, ITC, tax paid and other annual GST details | Turnover, tax and other reconciliation differences |
| Relationship Between Forms | Main annual return | Filed along with GSTR-9 when applicable |
| Certification | Furnished by the registered taxpayer | Self-certified under the current framework |
Businesses should not assume that filing GSTR-9 automatically completes the entire annual compliance process. If GSTR-9C applies, the reconciliation statement must also be completed.
Once the regular returns and reconciliations are complete, businesses can proceed with annual-return filing through the GST portal.
Visit www.gst.gov.in and log in using the relevant GSTIN credentials.
Select the financial year 2025–26 and navigate to the annual-return section under the relevant return-filing menu.
Confirm that all applicable GSTR-1 and GSTR-3B returns for FY 2025–26 have been filed.
If the GSTR-9 or GSTR-9C option is unavailable, first check for outstanding periodic returns and other portal requirements.
The portal may populate information using data already available from filed returns and statements.
Review the figures carefully. Auto-populated information is a starting point for verification, not a replacement for reconciling the underlying records.
Compare annual turnover, tax liability, ITC and other relevant information against the accounting records and filed returns.
Investigate material differences before proceeding.
Complete the relevant sections of GSTR-9 based on the taxpayer’s circumstances and the applicable form instructions. Review HSN reporting, amendments, ITC details and tax-payment information wherever relevant.
If GSTR-9C applies, prepare the reconciliation statement using the final financial statements and supporting workings.
Check the completed forms, supporting calculations and applicable tax implications. Obtain the required internal approval before submission.
Complete the prescribed filing process using the authorised signatory or applicable electronic verification method.
Download and retain the filed return, acknowledgement, reconciliation statements and supporting working papers.
Preparing the relevant records in advance can make annual-return filing more efficient and reduce last-minute corrections.
Businesses should generally keep the following documents ready:
The exact records required will depend on the nature of the business, its transactions and the applicable filing requirements.
One of the most important parts of annual GST compliance is understanding why different records may show different figures.
GSTR-1, GSTR-3B, GSTR-2B and the books of accounts each serve a different purpose. They should be reviewed together rather than treated as interchangeable records.
Start with the sales register and compare the recorded outward supplies with GSTR-1.
Check the taxable value, tax rate, GSTIN details, credit notes, debit notes, amendments and the classification of supplies. Also review whether transactions have been reported in the correct period.
Differences may arise because an invoice was omitted, an amendment was reported later or a credit note was recorded differently in the books and GST returns.
Each material difference should have a clear explanation supported by documents.
After checking the sales information, compare the applicable tax liability with the amounts declared in GSTR-3B.
Review the tax payable under the relevant heads, reverse-charge liability, tax paid and adjustments reported during the year.
A difference between GSTR-1 and GSTR-3B should not be dismissed as a routine accounting issue. Determine whether it reflects a reporting error, a timing difference or an actual short-payment of tax.
Where a liability difference is identified, the correct treatment should be determined under the applicable GST provisions.
Compare purchase records and eligible input tax credit with GSTR-2B and the ITC actually claimed or reversed in GSTR-3B.
Investigate missing invoices, duplicate claims, supplier reporting differences, credit notes, ineligible credit and timing issues.
An invoice appearing in GSTR-2B does not, by itself, establish that the credit is eligible. The taxpayer must satisfy the applicable legal conditions and restrictions.
Finally, compare the figures used in the annual return with the relevant accounting records and financial statements.
Differences may arise because of advances, credit notes, the sale of fixed assets, exempt supplies, timing differences or the treatment of certain transactions.
The objective is not to force every figure to match. It is to identify the reason for each material difference, determine its correct tax treatment and maintain evidence supporting the conclusion.
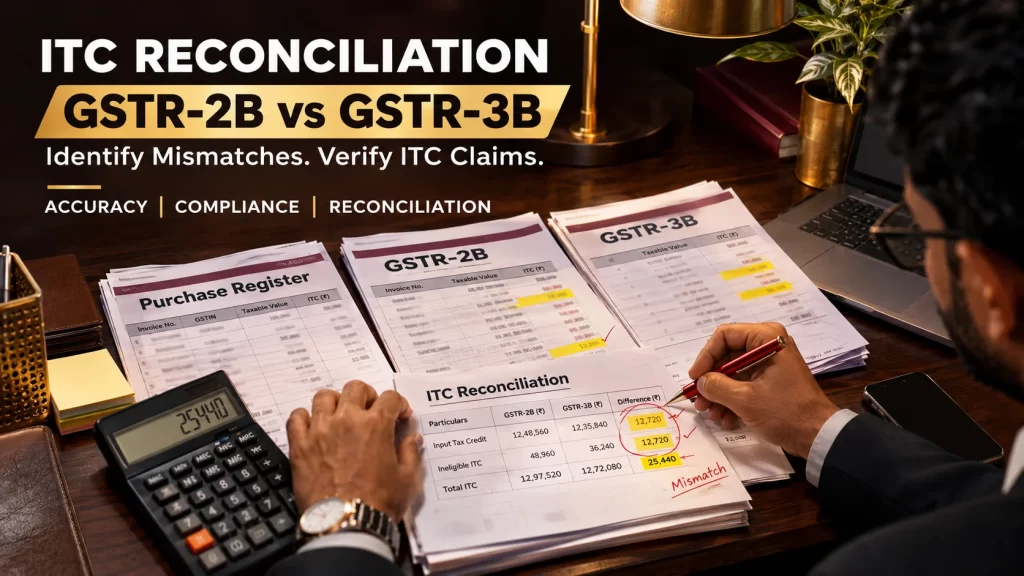
Consider a business that is preparing its annual GST reconciliation for FY 2025–26.
Its working papers show the following illustrative figures:
| Particulars | Amount |
|---|---|
| ITC supported by the books and invoices before final eligibility checks | ₹5,00,000 |
| ITC reflected in GSTR-2B for the comparison | ₹4,60,000 |
| Difference Requiring Investigation | ₹40,000 |
The ₹40,000 difference should not automatically be claimed or treated as permanently ineligible.
The accounts team should identify the invoices contributing to the difference and check whether they relate to supplier reporting, timing, amendments, credit notes or other issues.
It should then verify the applicable ITC conditions, restrictions and deadlines before deciding on the appropriate treatment.
The final reconciliation should record the amount, the reason for the difference, the evidence reviewed and the action taken.
The deadline for claiming eligible ITC relating to FY 2025–26 is an important issue during November 2026.
Under Section 16(4) of the CGST Act, the general time limit for claiming ITC relating to invoices or debit notes for a financial year is 30 November following the end of that financial year, or the date of furnishing the relevant annual return, whichever is earlier, subject to applicable statutory provisions.
For FY 2025–26, this makes 30 November 2026 an important date for eligible ITC claims. Filing the relevant annual return earlier may bring the applicable cut-off forward.
Businesses should therefore review outstanding invoices, supplier reporting, ITC eligibility and required corrections promptly. They should not assume that an unclaimed amount can always be added after filing the annual return or after the statutory cut-off.
For the relevant provision, consult Section 16 of the CGST Act and obtain professional advice for complex or disputed ITC positions.
FY 2025–26 includes the GST rate changes effective from 22 September 2025. Businesses should therefore pay attention to transactions around the changeover rather than assume that the same tax rate applied throughout the year.
Review the applicable rate for relevant supplies, the dates and terms of the transactions, invoices and credit notes, and the corresponding reporting in GST returns.
Businesses should also examine whether any products or services became subject to a different rate or exemption and whether the corresponding accounting and tax treatment was applied correctly.
The correct treatment depends on the supply and the applicable legal provisions. A rate change should not be applied retrospectively to every transaction merely because the invoice relates to the same product or service.
Keep the supporting invoices, credit notes and relevant working papers available for the annual-return reconciliation.
Missing the applicable annual-return deadline may result in late fees under the relevant provisions of the CGST Act and corresponding state GST law, where applicable.
The financial impact depends on the taxpayer’s circumstances, the relevant statutory provisions and any applicable relief or notification. Businesses should not assume that an extension or waiver granted for an earlier financial year automatically applies to FY 2025–26.
For GSTR-9C, the calculation of the late fee for a delayed complete annual return has been clarified by CBIC Circular No. 246/03/2025-GST. Where GSTR-9C is required, the applicable late-fee calculation takes account of the date on which the complete annual return is furnished, as explained in the circular.
Late filing can also leave unresolved differences in turnover, tax liability and ITC for longer than necessary.
To avoid unnecessary compliance problems, businesses should complete their reconciliations, obtain approval and file the applicable forms within the prescribed time.
For the relevant clarification, refer to CBIC Circular No. 246/03/2025-GST.
Businesses preparing for annual-return filing should use a documented checklist rather than rely on memory during the final weeks of December.
November 2026
December 2026
An early review is preferable to leaving the entire process until the final few days of December, when unresolved differences may take time to investigate.
As of 7 November 2026, an official extension has not been verified. The normal statutory deadline is 31 December 2026. Check the latest CBIC notifications and GST portal announcements before filing.
An extension is possible only if the competent authority issues an applicable notification. Requests from professional associations or expectations of an extension do not change the existing deadline.
The normal deadline is 31 December 2026. Taxpayers required to file GSTR-9C must furnish the reconciliation statement along with the annual return within the applicable deadline.
The annual-return exemption generally applies to eligible taxpayers whose aggregate turnover does not exceed ₹2 crore, subject to the applicable notification and exclusions. Businesses should verify their eligibility before deciding not to file.
Generally, yes. Eligible registered taxpayers whose aggregate turnover exceeds ₹5 crore must furnish GSTR-9C along with GSTR-9, subject to the applicable exclusions.
GSTN has advised taxpayers to file all applicable GSTR-1 and GSTR-3B returns for FY 2025–26 before accessing the annual-return filing facility. Businesses should clear outstanding periodic returns first.
Businesses should review the return carefully before submission. They should not assume that a filed GSTR-9 can simply be revised like a periodic return. Any correction or subsequent action must be assessed under the applicable law and GST portal provisions.
Businesses should reconcile the books of accounts, sales and purchase registers, GSTR-1, GSTR-3B, GSTR-2B, tax payments, ITC reversals, credit notes and applicable HSN reporting.
Late filing may attract late fees under the applicable provisions. The amount and treatment depend on the circumstances and any applicable relief. Businesses should verify the current rules and complete the filing as soon as practicable.
GSTR-9C is the reconciliation statement furnished along with the annual return where applicable. Businesses should complete the required annual-return filing process in accordance with the GST portal instructions and applicable law.
Annual GST compliance involves more than submitting forms before a deadline. Businesses need reliable records, clear reconciliations and a proper understanding of differences between the books and GST returns.
AVC India provides GST compliance, return-filing, reconciliation and indirect-tax advisory services to businesses. Professional assistance can help identify unexplained differences, review ITC positions, organise supporting records and prepare the applicable annual-return documentation.
Our team can help businesses review:
If your business needs assistance preparing for the FY 2025–26 annual return, visit AVC India or explore our GST services in Gurgaon.
You can also read our guide to common GST compliance mistakes that trigger tax notices and our article on income tax scrutiny after GST mismatch for related compliance issues.